

How the Wealthy Use Life Insurance to Build Tax-Free Income — And How Veterans Can Too
Most people think life insurance serves one purpose — a payout when you die.
And for a long time, that's all most of us were taught to expect from it.
But here's what most military families were never shown:
Some of the wealthiest people in this country don't just use life insurance for protection.
They use it as a financial strategy.
One that grows money, reduces tax exposure, and creates income that lasts a lifetime.
This isn't a secret kept from the wealthy on purpose.
It's just never been explained to the people who need it most. Until now.
The Problem With How Most People Save for Retirement
If your entire financial plan is built around a 401(k), a Thrift Savings Plan (TSP), or market-based accounts, your future income is exposed to two risks that most people don't fully think through until it's too late.
Risk One: Market Losses
When the market drops, your account drops with it.
That's manageable when you're young and have decades to recover.
But if a significant loss happens close to retirement, or during it, that's a different story.
The timing of losses matters just as much as the losses themselves.
Risk Two: Taxes in Retirement
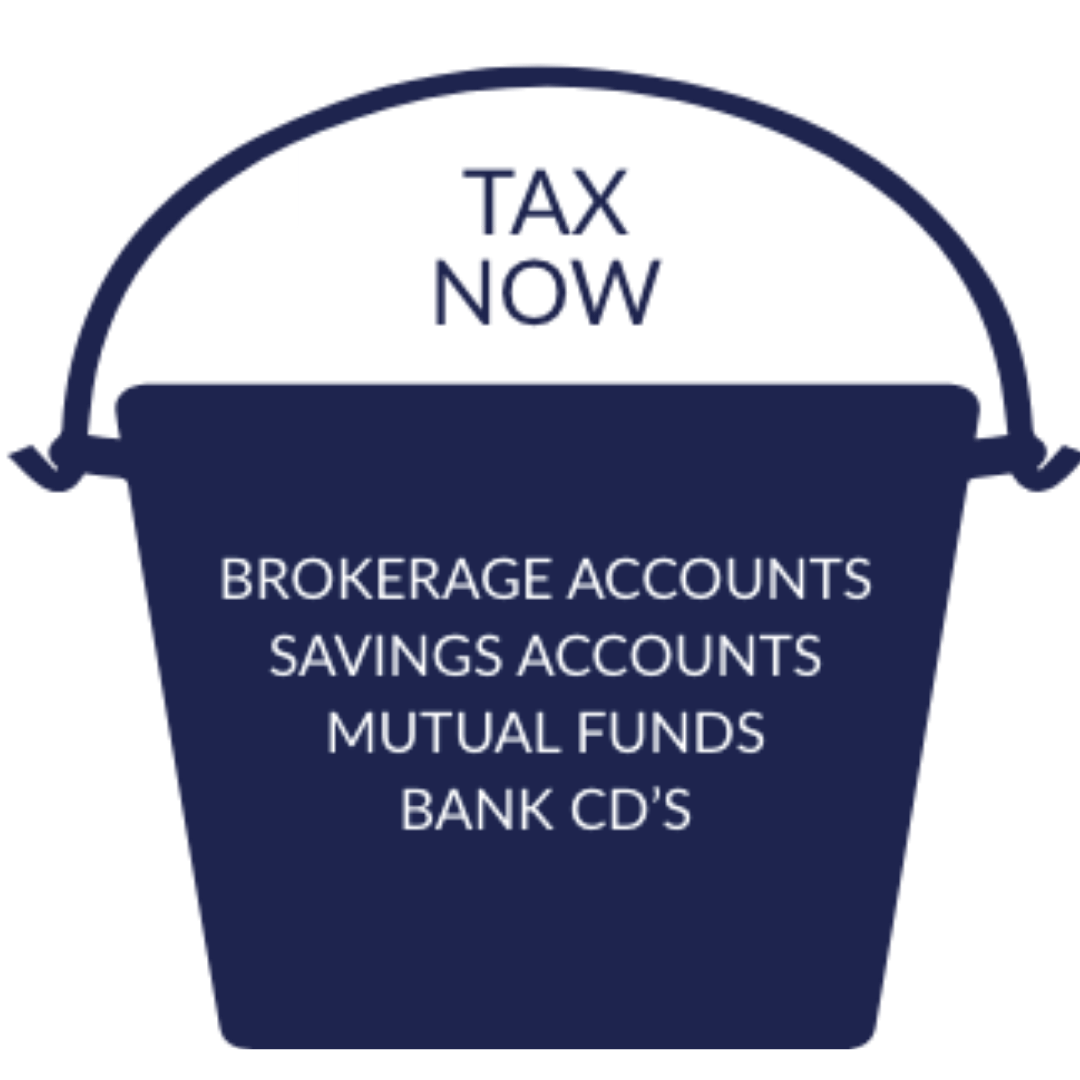
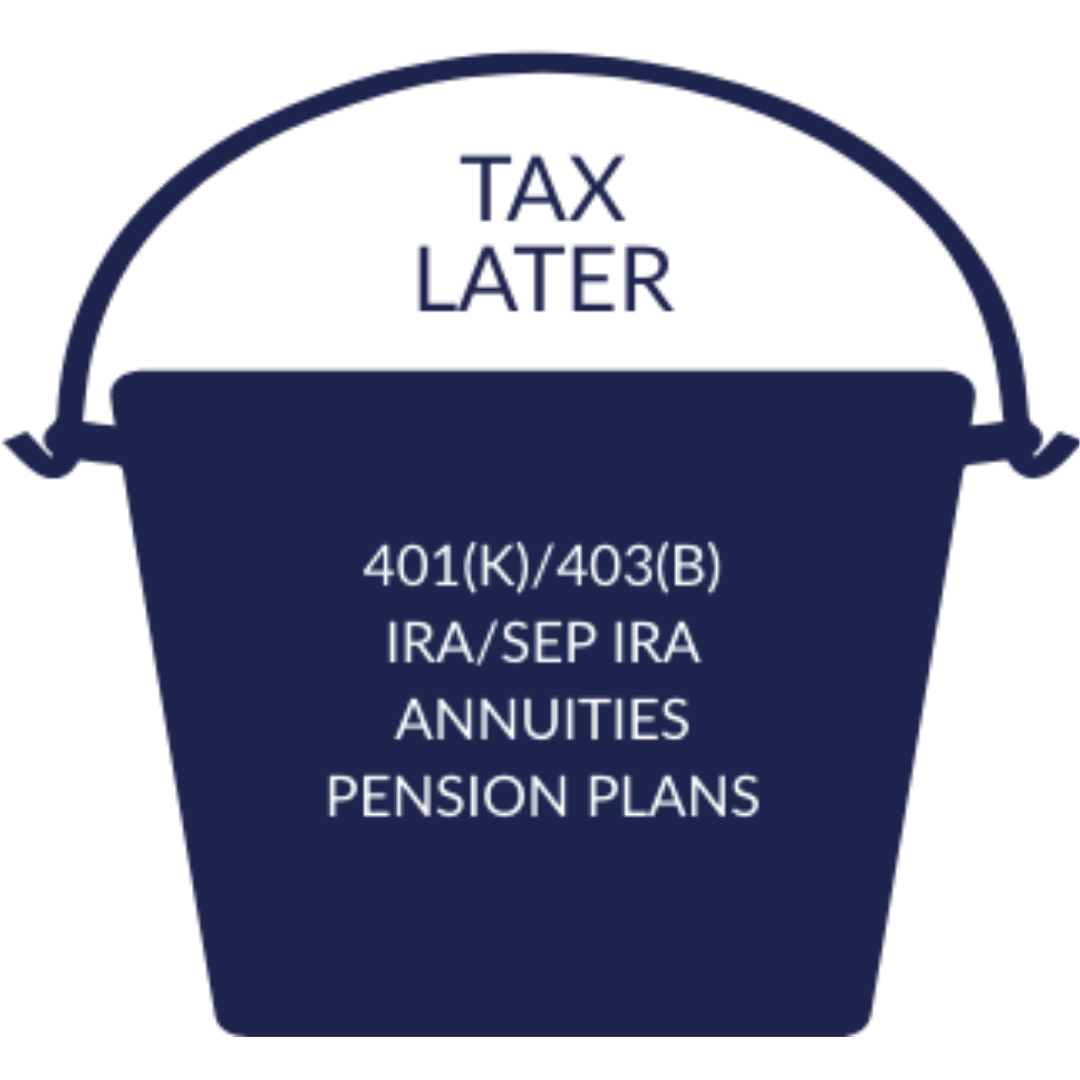
Most traditional retirement accounts are tax-deferred, not tax-free.
That's an important distinction.
You're not avoiding taxes.
You're delaying them.
When you start drawing that money down in retirement, that income gets taxed.
And depending on where tax rates are by then, that bill could be significant.
Tax-deferred and tax-free are not the same thing.
One delays the bill.
The other eliminates it.
Understanding the difference is one of the most important shifts you can make in how you plan for retirement.

What the Wealthy Do Differently
They don't rely on a single bucket of money.
They build multiple streams of income with different tax advantages, so no single market event or tax change can derail their entire plan.
One of the strategies that shows up consistently in those plans is an Indexed Universal Life policy, more commonly known as an IUL.
What Is an IUL — In Plain English
An Indexed Universal Life policy is a type of permanent life insurance that does three things at once:
It protects your family, builds cash value over time, and gives you access to that money while you're still alive.
But here's where it separates itself from traditional insurance products.
Growth Without Market Risk
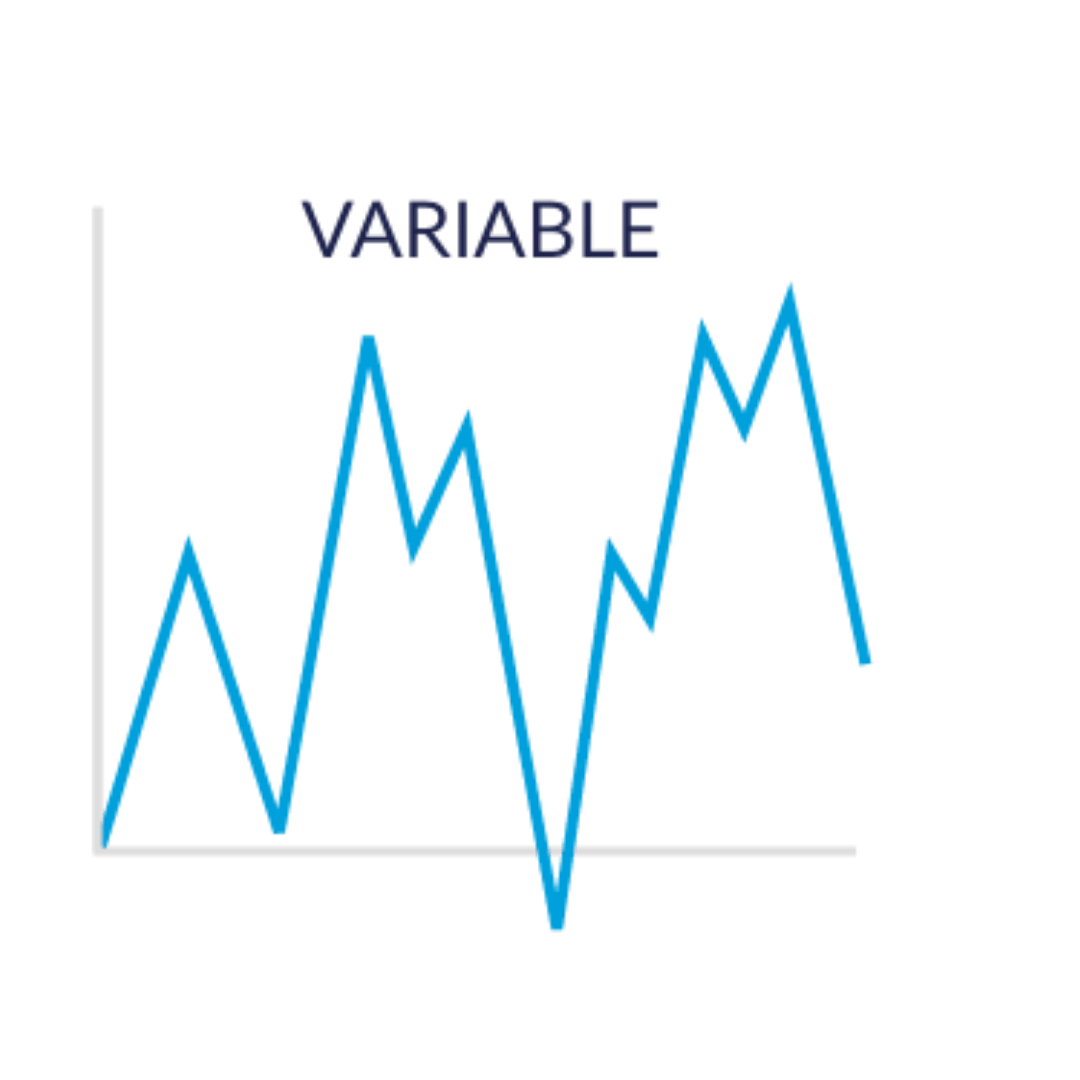
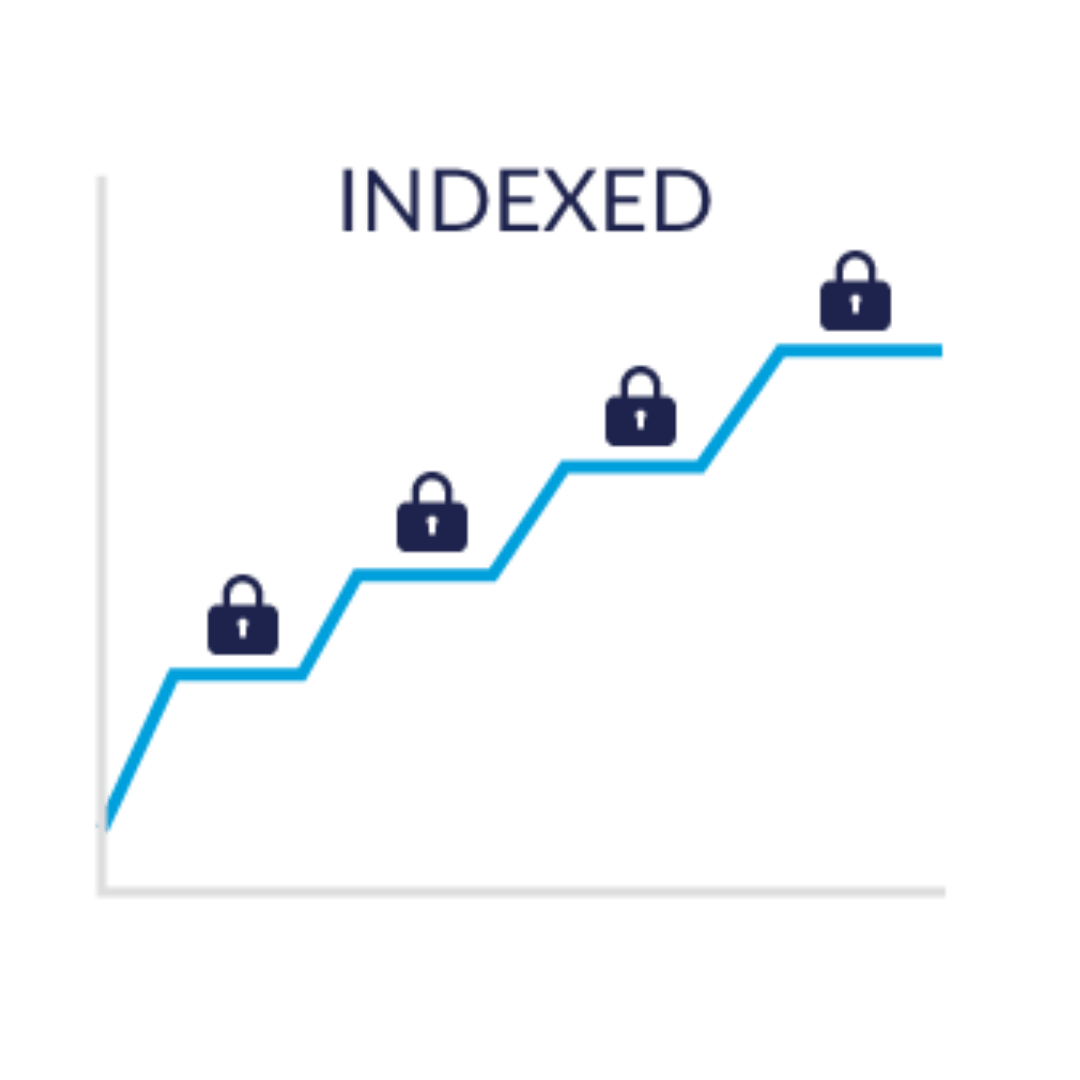
With an IUL, your cash value is linked to a market index like the S&P 500.
When the market goes up, your account has the potential to grow along with it.
When the market goes down, you are protected from those losses.
You get the upside potential.
Without the downside risk.
Let's say the market drops 30% in a single year.
If your retirement savings are fully exposed to the market, you feel every bit of that loss.
With a properly structured IUL, your cash value doesn't move because of market performance.
That kind of stability changes how you think about retirement entirely.
Tax-Advantaged Income You Can Actually Access
Here's what most people were never shown.
With the right structure, you can access your IUL funds in a way that is tax-advantaged, flexible, and not subject to the same required withdrawal rules as a 401(k) or TSP.
That means you can create an income stream in retirement without the same tax burden that comes with traditional accounts.
You're not waiting for a specific age.
You're not forced into a withdrawal schedule.
You access your money on your terms.
This Is Where the "Be Your Own Bank" Concept Comes From
Instead of borrowing from banks, pulling from volatile market accounts, or being pushed into taxable distributions, you can leverage your own policy.
Access your money when you need it.
Use it how you choose.
And keep your long-term strategy intact while you do it.
It's not a loophole.
It's how the policy is designed to work, when it's built correctly.
What Most People Get Wrong About IUL
They hear about it and assume it's too complicated, too expensive, or too good to be true.
Others jump in without fully understanding it, or worse, they get into a policy that was designed incorrectly.
And that's where real problems happen.
An IUL is not magic.
It's a tool.
And like any tool, it has to be used correctly to work the way it's intended.
A poorly structured IUL can underperform.
A well-structured one can be one of the most powerful financial tools in your plan.
How This Fits Into Your Overall Financial Plan
This isn't about replacing everything you're already doing.
It's about completing the picture.
Relying only on market-based accounts or employer-sponsored plans leaves gaps in your strategy, gaps that can become very costly over time.
An IUL, when structured correctly, can protect your family, grow your money, create tax-efficient income, and add a layer of stability that market-based accounts simply cannot provide on their own.
Where Most Veterans Start Connecting the Dots
Once this clicks, the next natural question becomes: what about the money I already have sitting in my TSP or 401(k)?
How do I protect what I've already built, and make sure it's working as hard as it can for my family?
That's exactly the conversation worth having.
New to IUL? Get the full breakdown first: Term vs. Whole Life vs. IUL — Which Life Insurance Is Right for Military Families?
What to Do Next
If this is the first time you're hearing any of this, that's completely normal.
These strategies exist, but they're rarely explained to the people who could benefit from them most.
Now that you know they're out there, the next step is understanding how they could apply to your specific situation.
That's not something you have to figure out alone.
I've spent nearly 20 years in the Army, and in that time I learned one thing above everything else, taking care of the people who depend on you is the most important job there is.
That's what drives me today.
As a veteran and licensed non-captive broker, I work with military families to build the financial protection that most of us were never taught about during our service.
It's personal to me.
Because I've been in your shoes.
Want to See How This Could Work for Your Family?
Most of the families I sit down with have never had anyone walk them through this clearly: what they have, what's missing, and what their options actually are.
That's my mission.
To make sure every military family has the knowledge and the protection they deserve.
We'll look at your full picture, talk through your options, and figure out what actually makes sense for where you are right now, together.
No pressure. No guesswork. Just clarity.
If you’re ready to get clear on your options, you can grab a time that works best for you below.
This is a quick, no-pressure call where we’ll walk through your situation and map out a strategy that actually fits your life.
YOU MAY ALSO LIKE
Categories
Newsletter
Subscribe to the newsletter and stay in the loop! By joining, you acknowledge that you'll receive our newsletter and can opt-out anytime hassle-free.