

Why SGLI Isn't Enough: What Every Veteran Needs to Know After Leaving the Military
Most veterans believe their benefits have them fully covered.
And during your time in the military that's mostly true.
But what most people don't realize is this: that protection doesn't follow you the same way when you leave.
And by the time many veterans find out, it's already too late to fix it the right way.
What SGLI Actually Does While You're Serving
Servicemembers' Group Life Insurance, or SGLI, is one of the best benefits we have while in uniform.
It offers affordable coverage of up to $500,000, and you're automatically enrolled from day one.
For most military families, it's their first real financial safety net.
And for good reason, it works well while you're serving.
SGLI is one of the strongest benefits available to active service members.
The problem isn't what it does during your service, it's what happens after.
What Most Service Members Are Never Told
SGLI is designed for your time in service, not for your life after it.
Once you separate or retire, your coverage doesn't just stay the same.
It changes.
It becomes more expensive.
And in many cases, it may not be enough anymore.
This isn't something the military spends a lot of time explaining.
And that gap in knowledge costs veterans and their families every single year.
What Happens to Your Coverage When You Leave
When you transition out, your SGLI typically converts to VGLI, Veterans' Group Life Insurance.
At first glance, that sounds like a smooth handoff.
But here's what that actually means in practice:
The Cost Increases Over Time
VGLI premiums are based on your age.
The older you get, the more you pay, and those increases can get steep.
What feels affordable at 35 may feel like a burden at 50.
No Cash Value
VGLI is purely insurance coverage.
There's no cash value that grows over time, no living benefits, and no way to access money while you're alive.
You pay in, and that's where it stays.
Limited Strategy and No Flexibility
VGLI cannot be customized.
It doesn't adapt to your life as your family grows, your income changes, or your goals shift.
There's no way to use it as part of a broader financial plan.
With VGLI, you're paying more over time for less control.
That's not a plan. That's a placeholder.
Where the Gap Happens
This is where most veterans get caught off guard.
They assume: "I've always been covered" or "I'll just keep what I have."
What they don't realize is that their coverage was never designed for long-term financial planning.
So when they start a family, buy a home, or begin thinking about retirement, they're relying on something that was never built for that stage of life.
The Risk Most People Don't Stop to Think About
Let's make this real for a moment.
If something happened to you tomorrow, would your current coverage pay off your home?
Replace your income?
Support your kids long-term?
Or would your family be left trying to figure it out on their own?
Because this isn't just about having insurance.
It's about having enough of the right kind of protection at every stage of your life.
What Most Veterans Do Instead — And Why It Costs Them
They wait.
They assume they'll figure it out later.
And later turns into higher premiums, fewer options, and health changes that limit what they qualify for.
The earlier you plan, the more control you have.
That's not a scare tactic, it's just how insurance works.
Time is one of the most valuable tools you have, and most people don't use it.
Waiting doesn't protect your options, it shrinks them.
The best time to build your plan is before you need it.
A Better Approach to Life After Service
Instead of relying only on what the military provided, the goal is to build a strategy that stays with you for life, adapts as your family grows, and both protects and builds at the same time.
That could look like:
Term insurance for immediate, affordable protection during high-responsibility years.
Permanent coverage for long-term security that never expires.
Growth-focused strategies, like an IUL, that allow your money to work for you while you're still alive.
Not sure which type of coverage fits your situation?
Start here: Term vs. Whole Life vs. IUL — Which Life Insurance Is Right for Military Families?
What to Ask Before You Rely on Your Current Coverage
Whether you're still serving, preparing to transition, or already out, ask yourself these three questions:
What happens to my policy long-term?
Will this still make sense 10 to 20 years from now?
Is my family fully protected, or just partially?
Because the goal isn't just to have coverage. It's to have a plan.
Let Me Show You Exactly Where You Stand
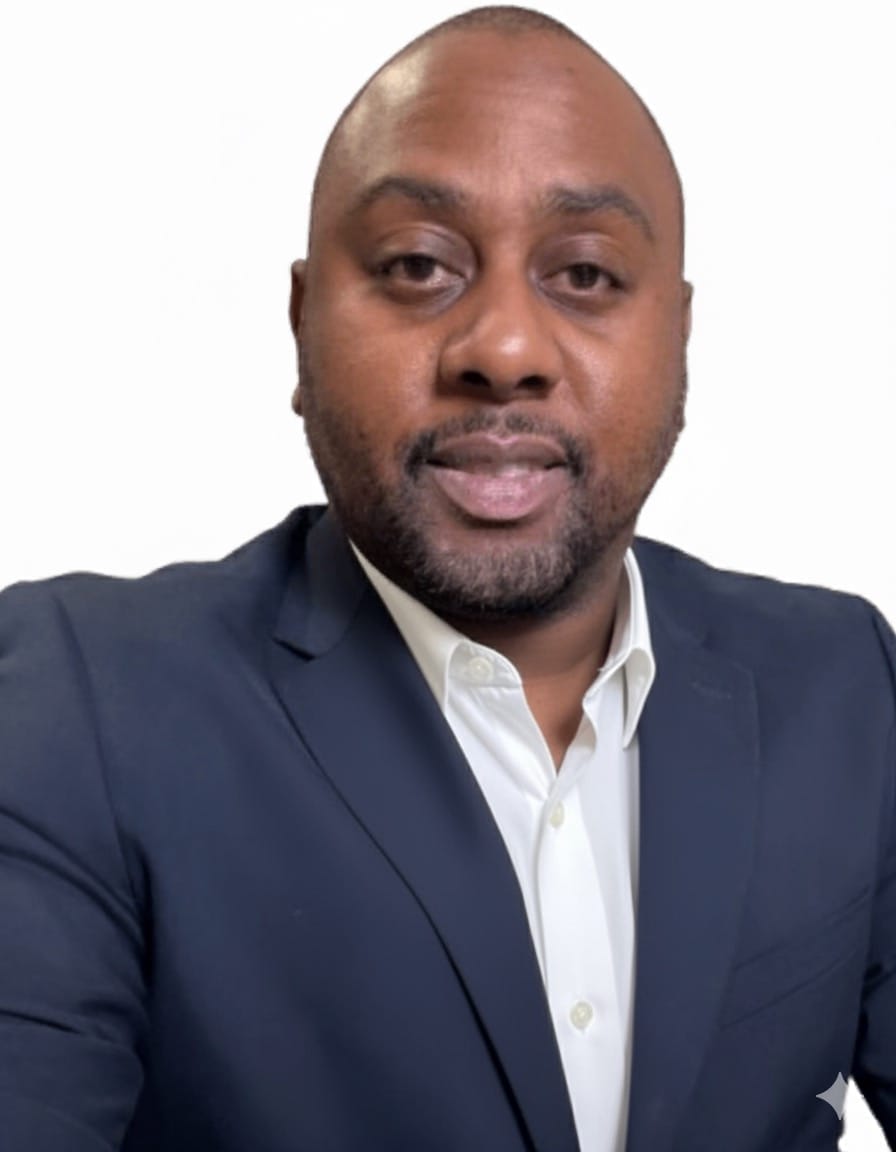
I've spent nearly 20 years in the Army, and in that time I learned one thing above everything else, taking care of the people who depend on you is the most important job there is.
That's what drives me today.
As a veteran and licensed broker, I work with military families to build the financial protection that most of us were never taught about during our service.
It's personal to me. Because I've been in your shoes.
I know what it feels like to want to do right by your family and not know where to start.
That's exactly why I do this work.
We'll sit down, look at your situation honestly, and figure out what actually makes sense for you, no pressure, no sales pitch, just a real conversation with someone who's been where you've been.
I've sat down with a lot of veterans who thought they had it figured out, until we actually looked at everything together.
That conversation has a way of bringing real peace of mind.
My mission is simple: to make sure military families have the knowledge and the protection they deserve, and that nobody walks away confused about where they stand or what their options are.
We'll look at your situation, talk through your options, and find what actually makes sense for you, together.
No pressure. No assumptions.
Just an honest conversation with someone who gets it.
If you’re ready to get clear on your options, you can grab a time that works best for you below.
This is a quick, no-pressure call where we’ll walk through your situation and map out a strategy that actually fits your life.
YOU MAY ALSO LIKE
Categories
Newsletter
Subscribe to the newsletter and stay in the loop! By joining, you acknowledge that you'll receive our newsletter and can opt-out anytime hassle-free.