

The TSP Tax Trap: What Most Veterans Don't Realize Until It's Too Late
You did everything right. You contributed consistently, stayed the course, and built something real inside your Thrift Savings Plan. That takes discipline, and it matters.
But here's the part most people were never told: that number you see in your TSP account isn't the number you actually get to keep.
Not even close.
The First Problem: You Haven't Paid Your Taxes Yet
Your TSP is a tax-deferred account.
That distinction is more important than most people realize.
It doesn't mean your money is tax-free, it means the tax bill has been pushed to later.
And later is coming.
Every single dollar you withdraw from your TSP in retirement is treated as taxable income.
So if you've built up $300,000, $500,000, or well over a million dollars, that entire balance is sitting in an account that the IRS still has a claim on.
Tax-deferred means you delayed the bill, not eliminated it.
The account balance you see today is not your retirement income.
It's your retirement income before taxes.
The Second Problem: Your TSP Is Still Exposed to the Market
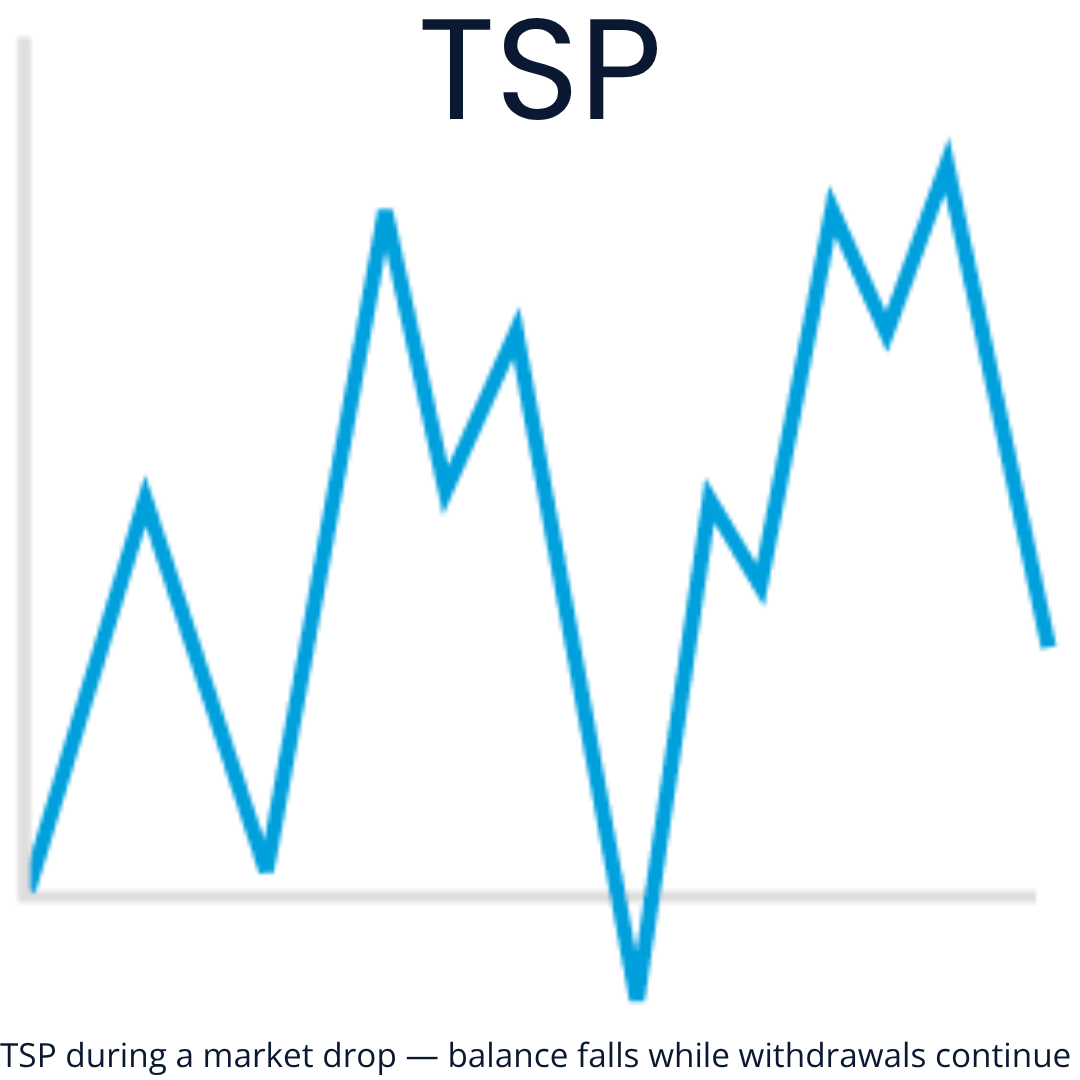
Your TSP is invested in market-based funds.
Which means when the market drops, your account drops with it.
For most of your career, that's manageable, markets recover, and you have time on your side.
But here's where it gets dangerous.
What Happens When the Market Drops at the Wrong Time
If the market takes a significant hit right before you retire, or during retirement while you're actively withdrawing ,the damage is compounded.
You're not just riding out a temporary dip.
You're pulling money out of a shrinking account and locking in those losses permanently.
This is called sequence of returns risk.
It's one of the leading reasons people burn through their retirement savings faster than they ever expected.
It's not just about how much your account grows.
It's about what the market is doing at the exact moment you need to start using it.
That timing can make or break a retirement plan.
Why This Hits Veterans Harder Than Most
Many veterans build their retirement plan around three pillars, their TSP, their pension, and their VA benefits.
On paper, that combination looks solid.
And it can be.
But if your TSP takes a major hit at the wrong time, or your withdrawals are taxed more heavily than you anticipated, that foundation starts to crack.
And by the time most people realize it, they have very little room left to recover.
Let's Make This Real With Actual Numbers
Say you need $60,000 per year to live comfortably in retirement.
If that income is coming from your TSP, you can't just withdraw $60,000.
After federal taxes and potentially state taxes depending on where you live, you may need to pull $70,000, $75,000, or more just to net what you actually need.
Now add a down market on top of that.
You're withdrawing more than planned from an account that is already shrinking.
You're locking in losses while simultaneously paying taxes on money you're pulling out.
That's the trap.
And most people don't see it coming until they're already in it.
The goal in retirement isn't just to have money saved.
It's to keep as much of it as possible and make sure it lasts.
Two very different problems that require two very different strategies.
This Isn't About Abandoning Your TSP
Your TSP is not the problem.
The problem is having no strategy around it.
Because what most veterans don't realize is that they may have more options with that money than they were ever told about.
One Strategy Worth Understanding: The Fixed Indexed Annuity
For some veterans, repositioning a portion of their TSP into a Fixed Indexed Annuity, or FIA, is worth a serious look.
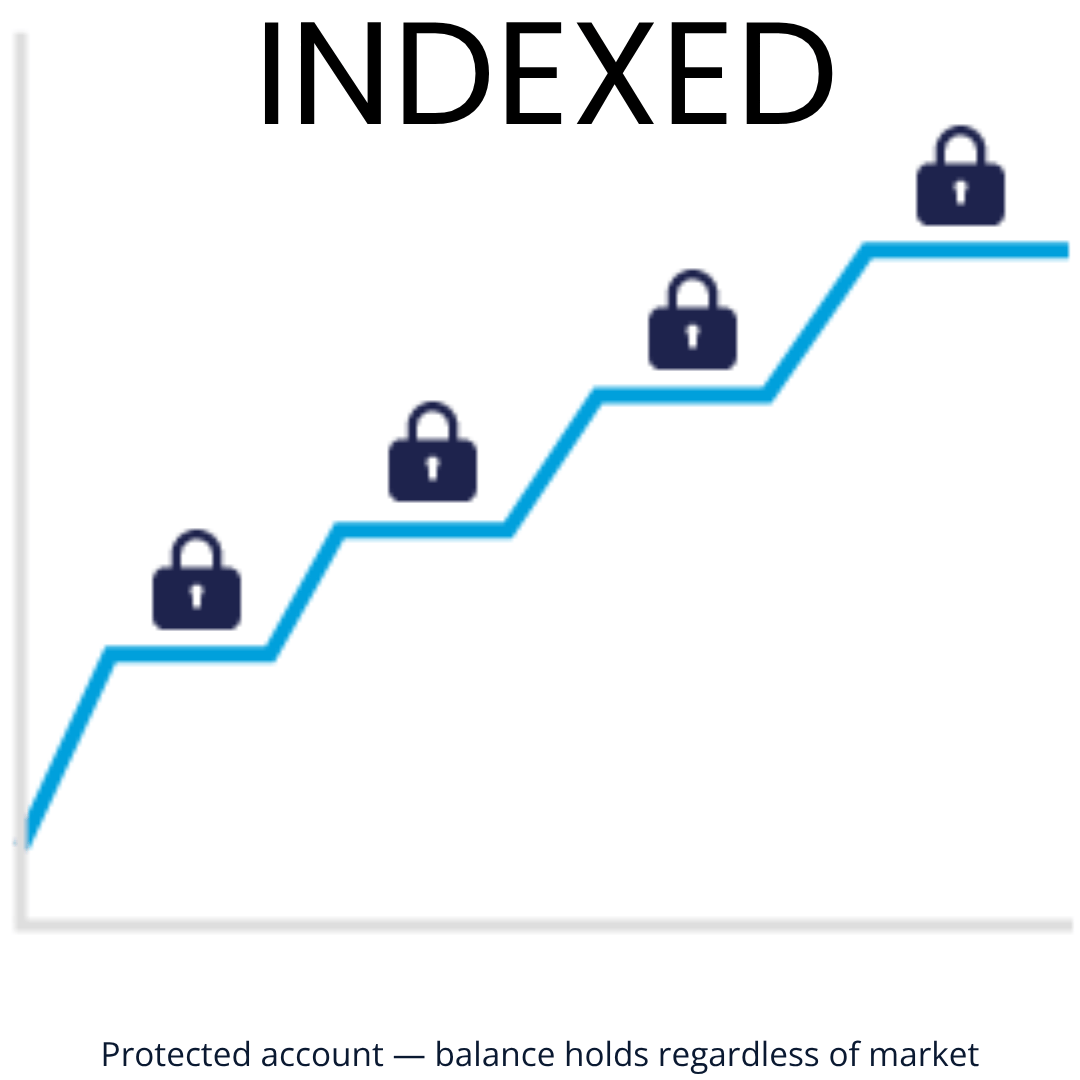
An FIA is designed to do three things: protect your principal from market losses, provide consistent and predictable growth, and create income you genuinely cannot outlive.
And in many situations, this repositioning can be done through a rollover process without triggering taxes or penalties at the time of transfer, depending on your specific situation.
An FIA won't make you rich overnight.
But it can do something just as valuable, make sure you never run out of money.
For a lot of families, that kind of certainty is worth more than the possibility of higher returns.
The Strongest Retirement Plans Don't Rely on One Account
They combine growth, protection, and income from multiple sources, each one serving a different purpose.
Growth for the long term.
Protection for stability.
Income for the years when you need it most and can least afford a loss.
That balance is what a real retirement strategy looks like.

How Everything Starts to Connect
Once you understand how your TSP is taxed, and how market risk can affect it at the worst possible moment, the picture becomes a lot clearer.
The question shifts from "how do I grow this?" to "how do I protect what I've already built, and make sure it actually lasts?"
That's the right question.
And it's one worth answering before retirement is right around the corner.
Want to understand how an IUL fits into this picture alongside your TSP strategy?
Start here: How the Wealthy Use Life Insurance to Build Tax-Free Income — And How Veterans Can Too.
What to Do Before It's Too Late
The closer you get to retirement, the less room you have to recover from mistakes.
Ignoring your TSP strategy isn't a neutral decision, it's a costly one.
The families who come out ahead aren't the ones who earned the most.
They're the ones who planned early, understood their options, and made intentional decisions while they still had time.
You've already done the hard part by building something.
Now let's make sure you get to keep it.
I spent nearly 20 years in the Army, and in that time I learned one thing above everything else, taking care of the people who depend on you is the most important job there is.
That's what drives me today.
As a veteran and licensed broker, I work with military families to build the financial protection that most of us were never taught about during our service.
It's personal to me. Because I've been in your shoes.
Let's Look at What Your Options Actually Are
Choosing the right coverage doesn't have to feel overwhelming.
Most people just need someone to sit down with them, listen, and walk them through it honestly without an agenda.
That's exactly what I do.
We'll look at where you are right now, what your family needs, and where you want to be.
Then we'll build something that actually makes sense for your life, not a generic plan pulled off a shelf.
My mission is simple: every military family deserves to understand their options and feel confident about the decisions they're making.
You've put in the work. Now let's make sure your family is protected the right way.
No guesswork. No pressure. Just an honest conversation with someone who gets it.
Ready to get clear on where you stand?
Grab a time below that works for you.
It's a straightforward, no-pressure conversation where we'll walk through your situation and map out a strategy built around your life, not a template.
YOU MAY ALSO LIKE
Categories
Newsletter
Subscribe to the newsletter and stay in the loop! By joining, you acknowledge that you'll receive our newsletter and can opt-out anytime hassle-free.